Custom Shower Doors: Transform Your Bathroom Today
March 19th, 2026
Lily Kadirov


A new bathroom is one of the most common reasons homeowners borrow, and there is more than one way to pay for it. The right choice depends on how much equity you have, how quickly you need the money and how long you want to be paying it back. Below we walk through seven options, what each one suits, and how to set a budget before you apply for anything.
Financing works best when it is built on a firm number. Bathroom projects vary a lot because scope and finishes vary a lot, so a guess from a calculator is a weak place to start.
For our work in the Sacramento area, bathroom remodels start at $14,900. A bathroom refresh usually runs about $15,000 to $20,000. A shower remodel or tub-to-shower conversion is about $20,000 to $45,000, and a full primary bathroom runs $35,000 to $100,000 or more. Our bathroom remodel cost guide explains what moves a project from one range to the next.
Every project gets a free estimate with fixed, transparent pricing, so you know the figure before you choose how to pay it.
We offer 0% financing for 18 months on qualifying projects. For many homeowners this is the simplest route, because it is arranged alongside the estimate and there is no separate project to manage with a lender. Ask our team about current terms and eligibility during your consultation.
A home equity loan is a second mortgage. You receive the full amount at once and repay it with fixed monthly payments over a set term. It suits a project with a known price, like a full bathroom remodel with a signed estimate, because a fixed payment is easy to plan around.
A HELOC works like a credit line secured by your home. You draw what you need up to a limit and usually pay interest only on what you have used. Rates are often variable, so payments can change. A HELOC fits projects paid in stages, or homeowners who want a cushion for surprises found behind a wall.
A personal loan is unsecured. You get a lump sum and repay it in fixed installments, usually over a shorter term than equity financing. Approval depends on your credit, income and other debts rather than your home's value. This route can suit you if you have little equity, bought your home recently, or prefer to keep your house out of the loan.
A cash-out refinance replaces your current mortgage with a larger one and gives you the difference in cash. It can make sense when you would refinance anyway. It resets your loan term and comes with closing costs, so look at the cost of the whole new mortgage, not only the remodel portion.
If you are buying a home that needs work, a renovation mortgage can roll the purchase and the remodel into one loan. These make the most sense at the moment you buy or refinance. A mortgage lender can tell you whether your timing and project qualify.
Cash avoids interest entirely. Many homeowners pay part in cash and finance the rest, which keeps the balance smaller and the payment lighter. A credit card can cover a deposit or small purchases, but card rates are usually high once any introductory period ends, so it is rarely the best tool for the whole project.
This table compares the main options on how you receive the money, what secures it and what each one suits best.
| Option | How you get the money | Secured by your home? | Best for |
|---|---|---|---|
| Our 0% financing | Arranged with your project | Ask our team | Simple setup with your estimate |
| Home equity loan | Lump sum, fixed payments | Yes | A firm, known price |
| HELOC | Draw as needed | Yes | Staged payments, flexibility |
| Personal loan | Lump sum, fixed payments | No | Little equity or a fast start |
| Cash-out refinance | Cash from a new mortgage | Yes | Homeowners refinancing anyway |
The key difference is security. A home equity loan, HELOC or refinance is backed by your house, so missed payments put the home at risk. Borrow only what fits comfortably in your monthly budget.
Every lender sets its own rules, but most review the same few things:
Two loans with the same monthly payment can cost very different amounts over time. A simple routine helps:
If you are counting on a tax deduction for interest, ask a CPA or tax preparer whether your project qualifies before you rely on it.
Borrow the estimate plus a sensible cushion for choices you may change along the way. The tighter the scope at the start, the smaller that cushion needs to be. This is where a fixed price helps most: a loan sized to a firm number is far less likely to fall short halfway through the job.
Most financing stress comes from borrowing against a number that was never firm. The project grows, and the loan no longer covers it.
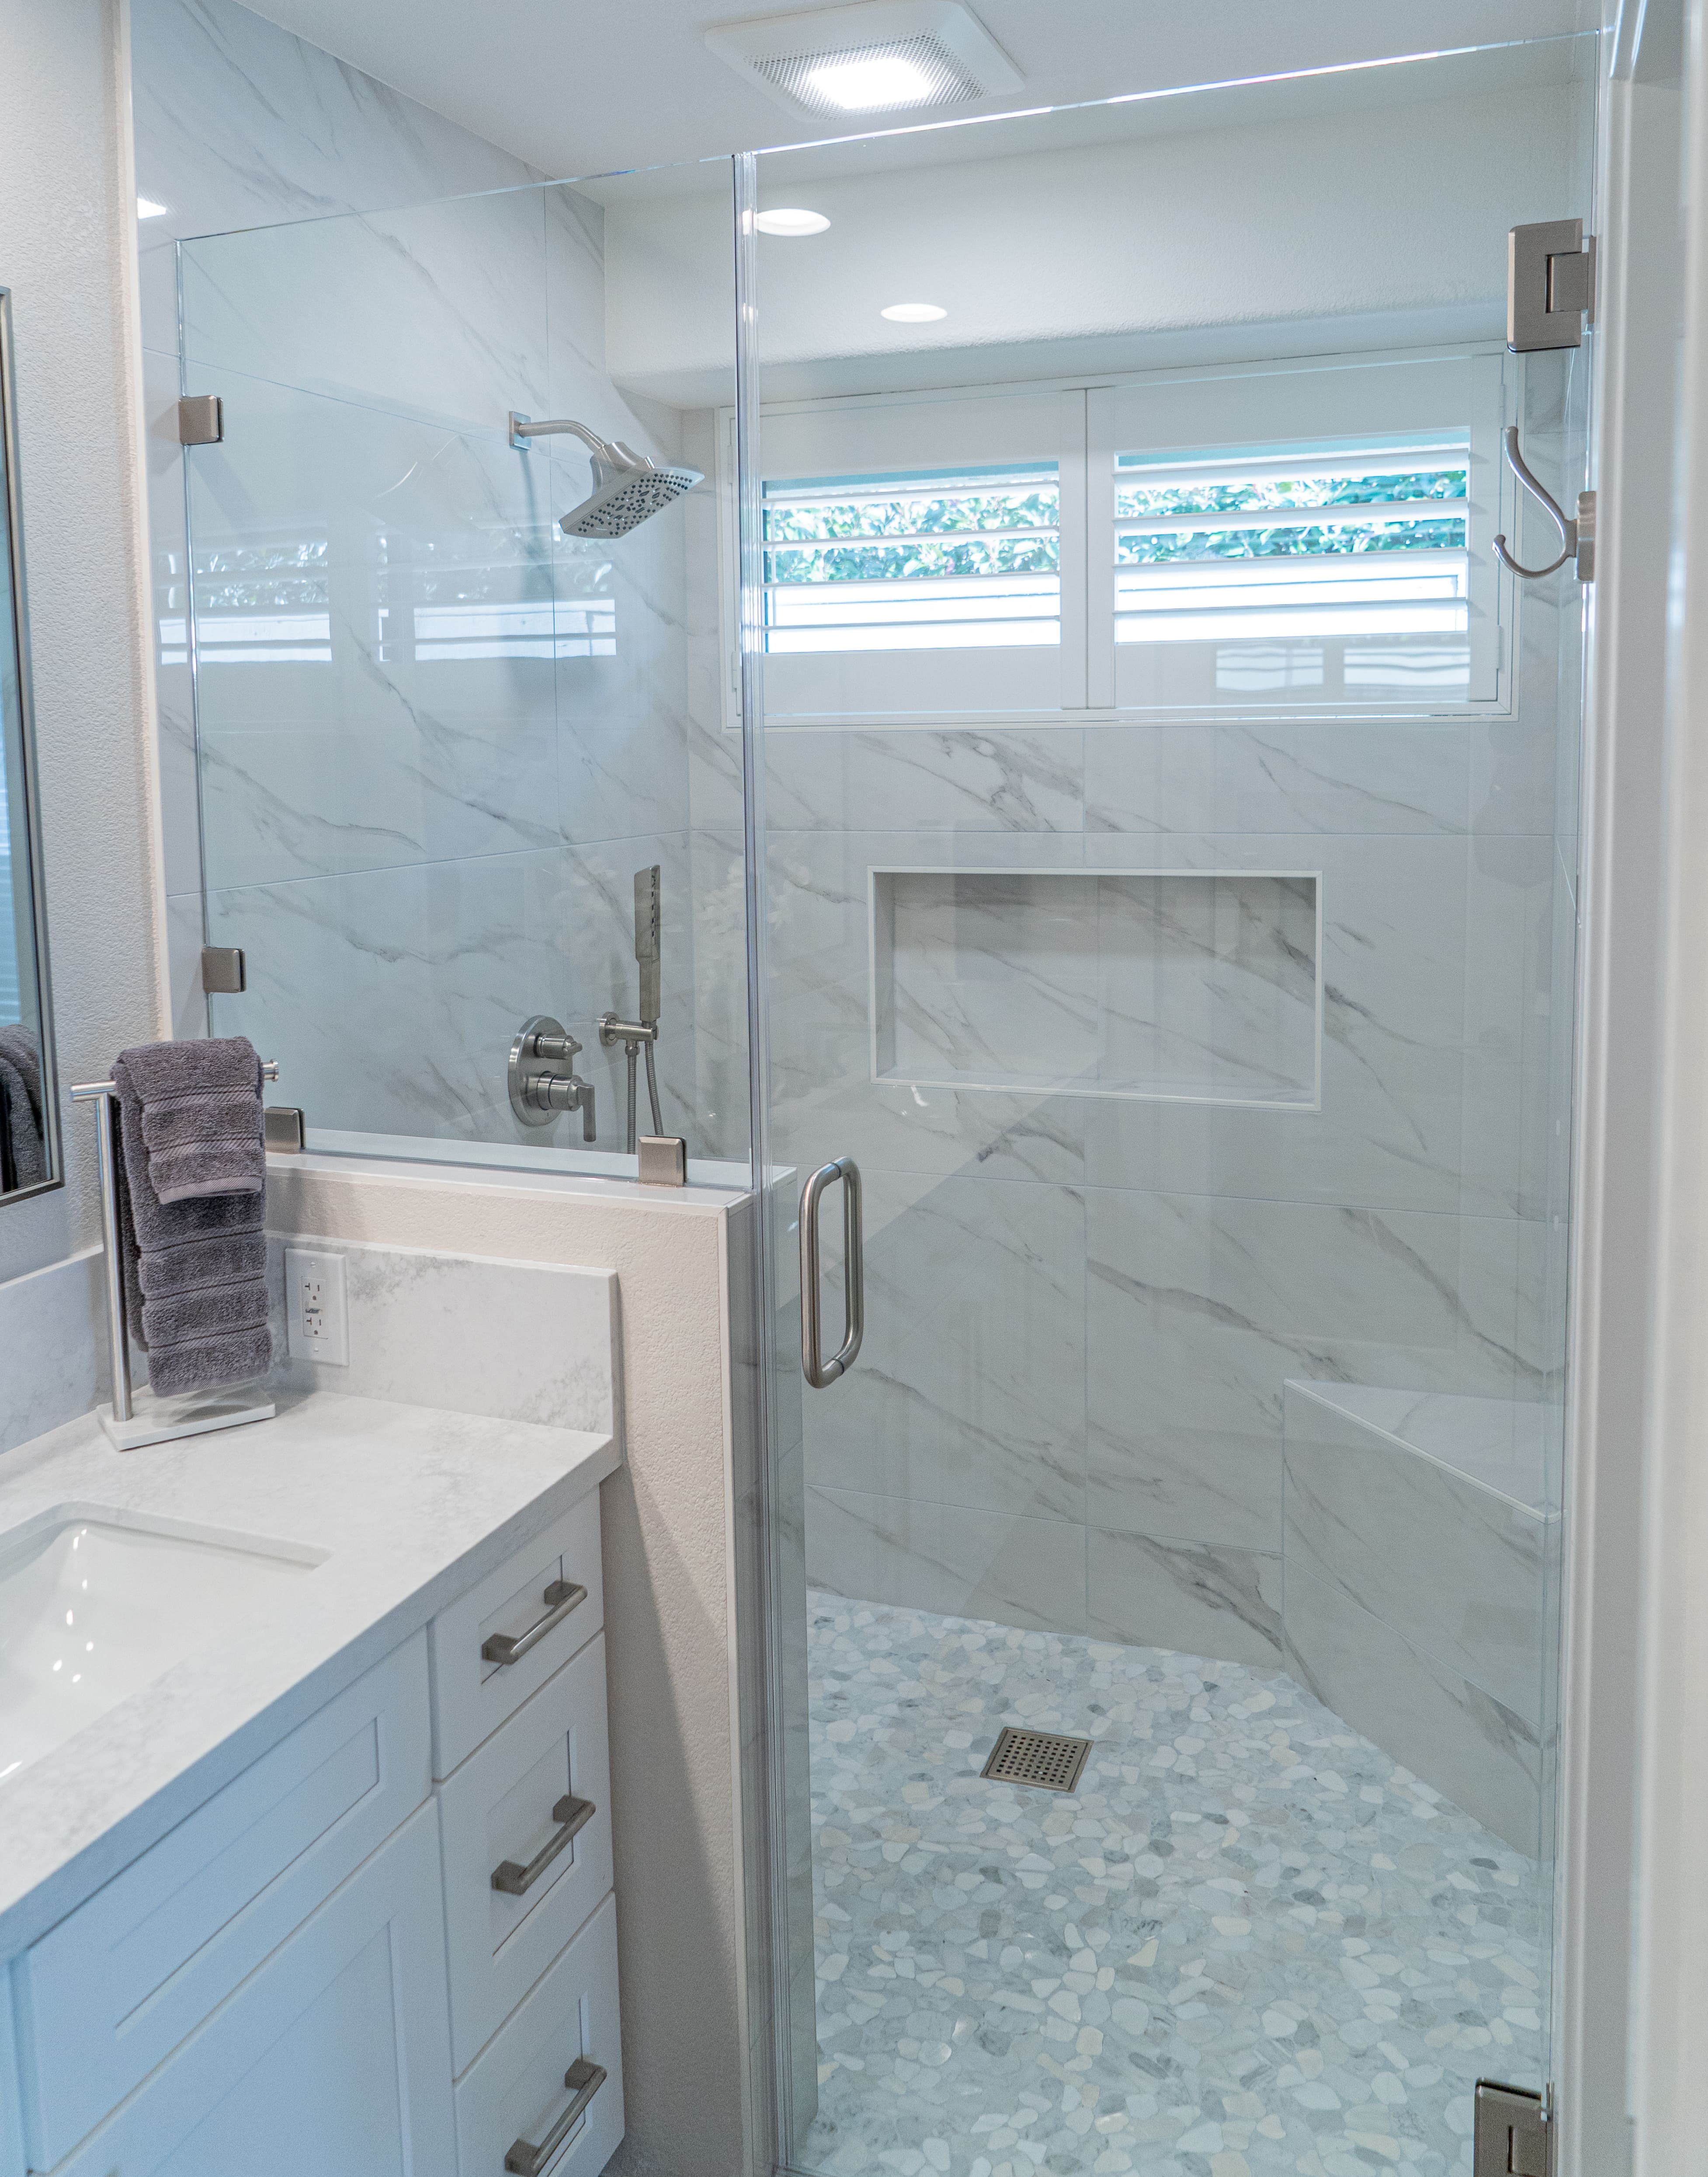
That is why we start with the estimate. We handle design, permits, project management, material procurement and installation, so the scope is set before work begins and the finished cost stays close to what you planned. With 10+ years of service and 200+ projects completed, we have seen how much smoother a remodel goes when the budget is settled first. See the result in our master bathroom remodel in Sacramento, or read about choosing a bathroom contractor in Sacramento.
Every home is different, so we confirm scope, pricing, financing options and any permit requirements for your project during a free consultation. Explore our bathroom remodeling services, then call Central Builders Inc. at (916) 347-7373 or request your free estimate.